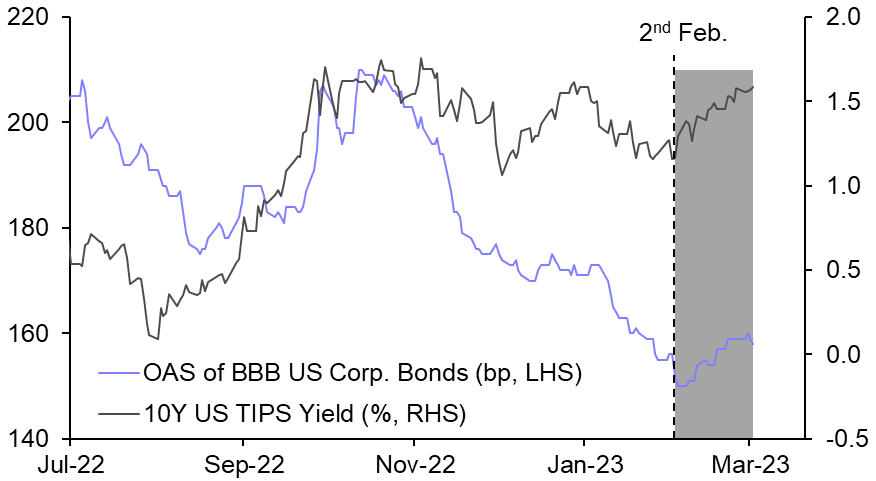
Capital Daily How is “higher for longer” playing out in the US stock market? Notwithstanding the partial recoveries today, the past month or so has seen a sell-off in both Treasuries and equities in which “rate sensitive” stock market sectors have underperformed. So long as... 3rd March 2023 · 7 mins read
US Economics Weekly Powell and payrolls to clarify rate outlook The February employment report and Fed Chair Jerome Powell’s testimony to Congress next week should give a clearer indication of whether recent talk of interest rates going “higher for longer” is... 3rd March 2023 · 6 mins read
Global Markets Update Two points on “higher for longer” and asset markets With much of the global economy holding up surprisingly well and inflation not coming down as quickly as expected, investors are weighing up the risk that policy rates remain elevated for much longer... 3rd March 2023 · 5 mins read
Capital Daily Three points on the latest rise in government bond yields Stronger-than-expected inflation and activity data have fuelled a further rebound in developed market (DM) government bond yields, posing upside risks to our policy rate forecasts. Even so, we think... 2nd March 2023 · 6 mins read
Europe Commercial Property Update Property returns to revive over the longer term The current economic downturn will mean that short-to-medium term property performance is under-par. But over a longer horizon, we expect real estate returns to reassert their traditional position... 2nd March 2023 · 3 mins read
US Employment Report Preview Employment growth to drop back to trend After the blowout 517,000 gain in January, we expect a more modest 200,000 increase in non-farm payrolls in February. But given the potential impact of weather and seasonality effects in January there... 2nd March 2023 · 4 mins read
US Data Response ISM Manufacturing Index (Feb.) The modest rebound in the ISM manufacturing index to 47.7 in February, from 47.4, leaves it firmly in contractionary territory. That should temper talk of a manufacturing resurgence on the back of... 1st March 2023 · 3 mins read
Bank of Canada Watch Too soon for pause to become permanent The fall in CPI inflation in January and stagnation in fourth-quarter GDP mean there is little chance of the Bank of Canada resuming interest rate hikes next week. But concerns about the tight labour... 1st March 2023 · 7 mins read
US Housing Market Data Response Mortgage Applications (Feb.) Stronger-than-expected economic data led to a resurgence in mortgage rates in February, which put a stop to a tentative recovery in mortgage applications for home purchase. This points to sales... 1st March 2023 · 2 mins read
US Housing Market Data Response Case-Shiller/FHFA House Prices (Dec.) Despite a sixth consecutive month of falling house prices in December, affordability was still stretched even before the renewed rise in mortgage rates. As a result, it is likely that prices will... 28th February 2023 · 3 mins read
Canada Data Response GDP (Q4) The stagnation in fourth-quarter GDP, together with the downward revision to third-quarter GDP growth, leaves the economy in worse shape than the Bank of Canada expected. That is another reason to... 28th February 2023 · 2 mins read
Capital Daily What to make of the yield curve phoney war With the US yield curve more deeply inverted than at any time since the early 1980s, it is worth (again) considering what the implications for financial markets are. 27th February 2023 · 5 mins read
US Data Response Durable Goods (Jan.) The 0.7% m/m rebound in core durable goods orders in January rounds off a month of strong activity releases and suggests business investment will hold up a bit better in the first quarter than we had... 27th February 2023 · 3 mins read