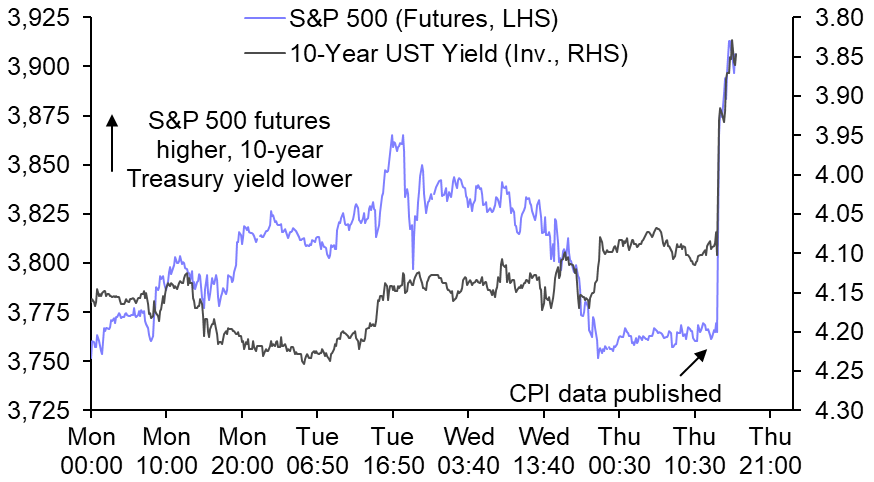
Capital Daily We doubt the dual rally in Treasuries and equities will last US Treasuries and equities rallied sharply after US CPI came in softer than expected, but we doubt this dual rally will persist. While we think Treasury yields will fall back further as the Fed... 10th November 2022 · 6 mins read
UK Economics Chart Pack Fiscal policy tightening just as the recession begins While the risk premium that pushed gilt yields up and the pound down after the mini-budget has mostly been reversed under the stewardship of Sunak and Hunt, the fear that the markets will baulk at any... 10th November 2022 · 9 mins read
Africa Economics Update Nigeria’s economy heading from bad to worse Nigeria’s demonetisation efforts are likely to add to already-high economic costs of the country’s unorthodox policies. The resulting currency falls will fuel inflation further and disruptions to... 10th November 2022 · 3 mins read
US Data Response Consumer Prices (Oct.) The better than expected 0.3% m/m increase in core consumer prices in October won’t on its own persuade the Fed to drop its hawkish stance. But we expect this to mark the start of a much longer... 10th November 2022 · 2 mins read
Latin America Data Response Brazil IPCA (Oct.) The fourth consecutive decline in Brazil’s inflation rate, to 6.5% y/y in October, will be welcomed by policymakers at the central bank. That said, inflation is still well above target and will stay... 10th November 2022 · 2 mins read
Global Central Bank Watch The signs of shifting cycles In recent weeks, attention has shifted from the likely size of rates hikes towards the timing of peaks and the prospect of ultimate cuts. History can tell us little about the likely profile since no... 10th November 2022 · 12 mins read
Middle East & North Africa Rapid Response Egypt Consumer Prices (Oct.) The acceleration in Egypt’s CPI inflation rate from 15.0% y/y in September to a four-year high of 16.2% y/y in October (consensus 15.6% y/y, CE 15.8% y/y) lends support to our view that policymakers... 10th November 2022 · 3 mins read
Nordic & Swiss Data Response Norway Consumer Prices (Oct.) October’s stronger-than-expected inflation data pose an upside risk to our forecast for the policy rate to peak at 3%. But with house prices falling, the Norges Bank faces a tricky balancing act. 10th November 2022 · 2 mins read
Emerging Europe Data Response Russia Consumer Prices (Oct.) Inflation in Russia fell more sharply than expected in October, to 12.6% y/y, but this won’t be enough to prompt the central bank to restart its easing cycle as policymakers are concerned about... 9th November 2022 · 2 mins read
Latin America Data Response Mexico Consumer Prices (Oct.) Mexico’s headline inflation rate came in at a weaker-than-expected 8.4% y/y in October and, while this is unlikely to prevent Banxico from delivering another 75pb interest rate hike, to 10.00%... 9th November 2022 · 2 mins read
China Data Response China Consumer & Producer Prices (Oct.) Consumer price inflation eased last month from September’s 29-month high and remained below the government’s preferred ceiling of 3%. It is set to stay low by global standards over the coming quarters... 9th November 2022 · 3 mins read
Europe Chart Pack ECB to keep hiking as stagflation intensifies The latest activity indicators show that the economy contracted in October, and the forward-looking measures of new orders and expectations suggest that the downturn will get worse. We have pencilled... 8th November 2022 · 11 mins read
Emerging Europe Economics Update Growth/inflation trade-off now a major test in Poland The Polish central bank’s dovish monetary policy stance is becoming increasingly at odds with the severity of inflation pressures and this reinforces our long-held view that inflation won’t return to... 8th November 2022 · 5 mins read
Australia & New Zealand Economics Update Energy price caps could knock off 1%-pt from inflation The proposed price caps on thermal coal and natural gas would knock off around one to 1.25%-pts from overall inflation though the full impact would only materialise in the second half of next year. 8th November 2022 · 4 mins read